
Coupang vs. Uber Technologies: Decelerating Versus Steady Revenue Growth
 2026-10-15 14:44
•Sarah Sidlow •The Motley Fool
••••••• •••••••
Axe Cap view
Uber's Steady Edge Over Coupang Signals Caution for E-commerce Bulls
Uber's consistent revenue growth contrasts sharply with Coupang's slowdown and regulatory hurdles.
Uber Technologies continues to lock in a steady revenue growth rate of around 27% annually and is sharpening its operating margins, hitting 13.3% recently. Its global reach—70+ countries—and moves in autonomous vehicles with Waymo and Zoox set it apart as a business with clear momentum. On the flip side, Coupang’s growth is stalling, margins remain negative, and ongoing regulatory headaches in South Korea add risk. For South African investors, this global tug-of-war matters because it reflects the challenges facing tech-driven platforms—not unlike Naspers or Prosus, which hold stakes in tech and e-commerce globally. These companies may face similar hurdles if regulatory pressures intensify or if growth slows unexpectedly. The USD/ZAR exchange rate will also factor in, as US dollar strength can weigh on local tech investments by making foreign earnings less valuable when converted back to rand. This view might be wrong if Coupang manages to stabilize growth or if Uber’s autonomous ventures stall, slowing its top-line momentum. this is just our opinion and not financial advice
Trim exposure to Prosus and Naspers, which have significant e-commerce exposure, and watch USD/ZAR closely as it will impact offshore earnings in rand terms.
- Prosus
- Naspers
- USD/ZAR
- Regulatory crackdowns on e-commerce in South Korea and globally
- Volatility in USD/ZAR affecting offshore earnings translation
6/10
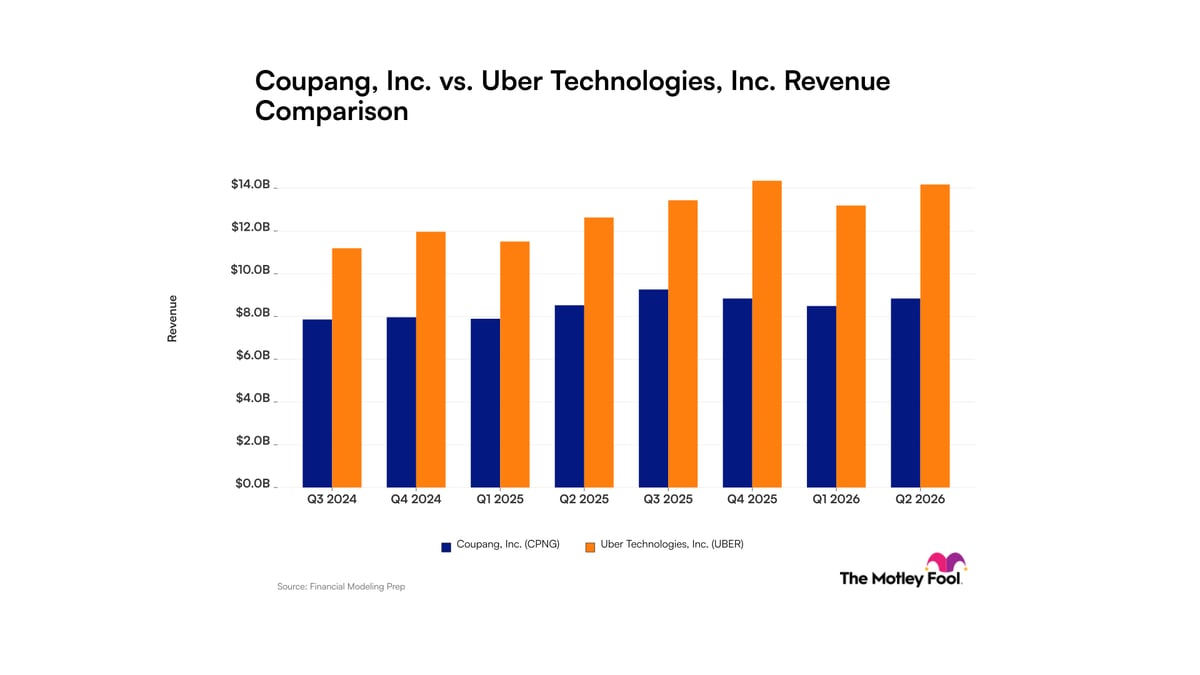
Uber Technologies demonstrates stronger revenue performance with consistent 27% growth over two years and improving operating margins, while Coupang faces slowing revenue growth, regulatory challenges, and negative operating margins. Uber's global platform across 70+ countries and autonomous vehicle partnerships position it favorably compared to Coupang's South Korea-focused e-commerce business, though both face litigation risks.
Our take is based on reporting first published by The Motley Fool.