GE Aerospace Is Spending $12 Billion on an Acquisition. Is It Still the Best Aerospace Stock to Own?
 2026-09-27 20:30
•Thomas Niel •The Motley Fool
••• •••••
Axe Cap view
GE Aerospace’s Bold Bet: What It Means for JSE Investors
GE Aerospace’s $12bn acquisition aims to cut costs and tighten supply chains, but South African investors should watch how this shakes global aerospace ties and the rand.
GE Aerospace’s move to buy Consolidated Precision Products is a big deal, even if it’s across the ocean. The $12bn price tag and a valuation near 26 times EBITDA suggest they’re betting big on squeezing out efficiency and better supply control. For South African markets, the direct link is thin—GE itself isn’t listed here—but the aerospace sector’s health nudges currency and industrial supply chains. A stronger GE could underpin dollar strength, meaning the rand might feel some pressure, particularly against the USD. Companies like Barloworld and Motus, tied to machinery import and transportation, could see margin squeeze if the rand weakens. If GE’s management missteps, or if global demand slows, the USD/ZAR could rebound less sharply, offering temporary relief. I’d watch the USD/ZAR closely here for signs of stress or resilience. this is just our opinion and not financial advice
Avoid direct aerospace plays on the JSE until dollar-rand volatility settles post-integration. Consider hedging USD/ZAR exposure or selectively trimming cyclical industrials sensitive to currency moves.
- USD/ZAR
- Barloworld
- GE deal execution fails
- Global aerospace demand slows
- Rand strengthens unexpectedly
6/10
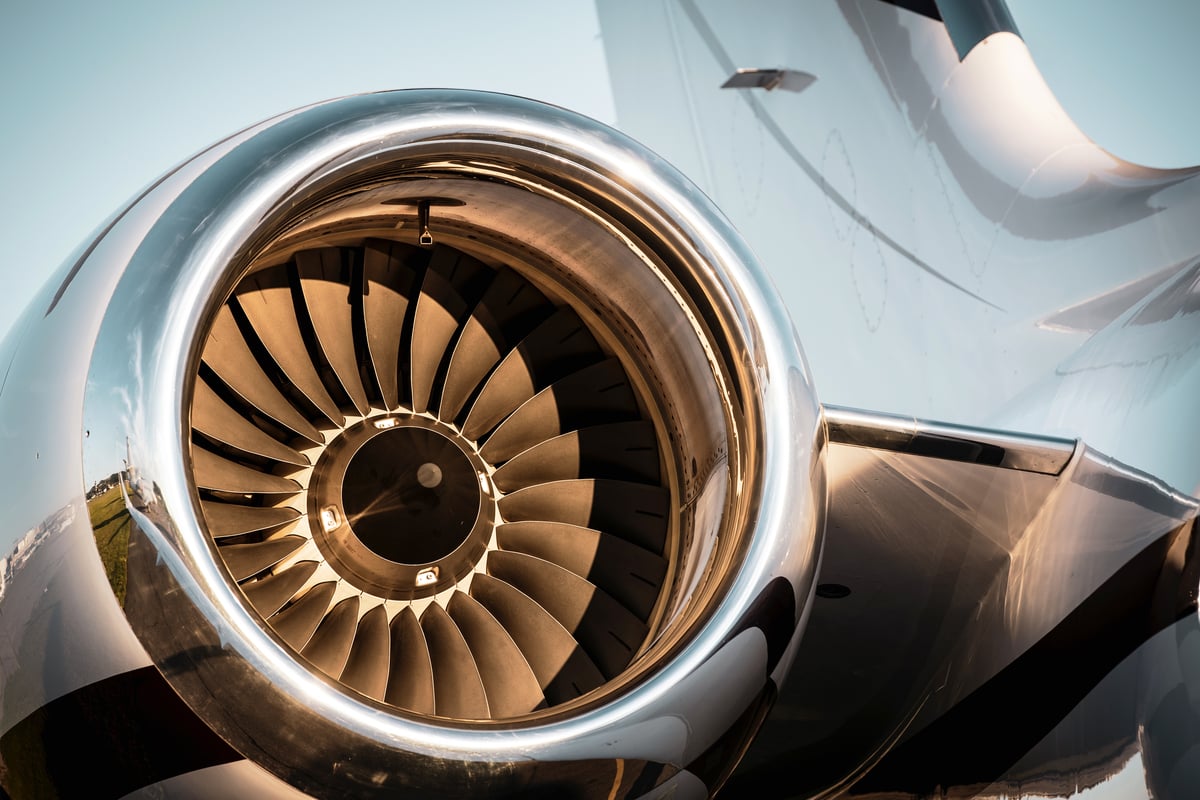
GE Aerospace announced a $12 billion acquisition of Consolidated Precision Products (CPP), its largest deal since becoming independent in 2024. The acquisition brings precision casting in-house, expected to create cost synergies, improve operational efficiency, and provide supply chain advantages. While the deal values CPP at 26x estimated 2027 EBITDA, effective valuation drops to 18x with synergies considered. Management expects the deal to be immediately accretive to earnings.
Our take is based on reporting first published by The Motley Fool.