Applied Materials vs. Qualcomm: What Revenue Trends Tell Investors About These Artificial Intelligence Companies
 2026-10-08 18:08
•Robert Izquierdo •The Motley Fool
••••• ••
Axe Cap view
Applied Materials Closing the Gap on Qualcomm in AI Race
AI is reshaping semiconductor demand and investors should reconsider exposure to these key players.
Applied Materials (AMAT) is riding a clear wave as AI chip demand fuels its semiconductor equipment sales, with revenue hitting record highs. This bodes well for companies supplying the AI infrastructure backbone. Qualcomm (QCOM), by contrast, faces a tougher path. Its traditional mobile handset market is maturing and revenue is rolling over, despite efforts to pivot toward AI data center chips. In South Africa, the direct stock plays are limited, so watching the USD/ZAR currency pair remains useful. A stronger dollar could pressure rand-earnings-sensitive tech stocks like Naspers and Prosus, which have significant overseas exposure. Meanwhile, local demand for AI hardware remains nascent, keeping the main action offshore. Investors should tilt toward exposure linked to AI infrastructure growth rather than legacy mobile tech. That might mean avoiding Qualcomm and watching Applied Materials indirectly through the rand and SA tech heavyweights. But if Qualcomm successfully repositions itself, especially in AI data centers, this view could change fast. this is just our opinion and not financial advice
Avoid Qualcomm for now given its revenue decline and uncertain AI pivot. Watch Applied Materials and consider indirect exposure via USD/ZAR and SA tech counters like Naspers and Prosus. Keep some dry powder for a potential Qualcomm turnaround.
- USD/ZAR
- Naspers
- Qualcomm's pivot to AI data centers gains traction
- Sudden rand depreciation hurting USD-linked valuations
6/10
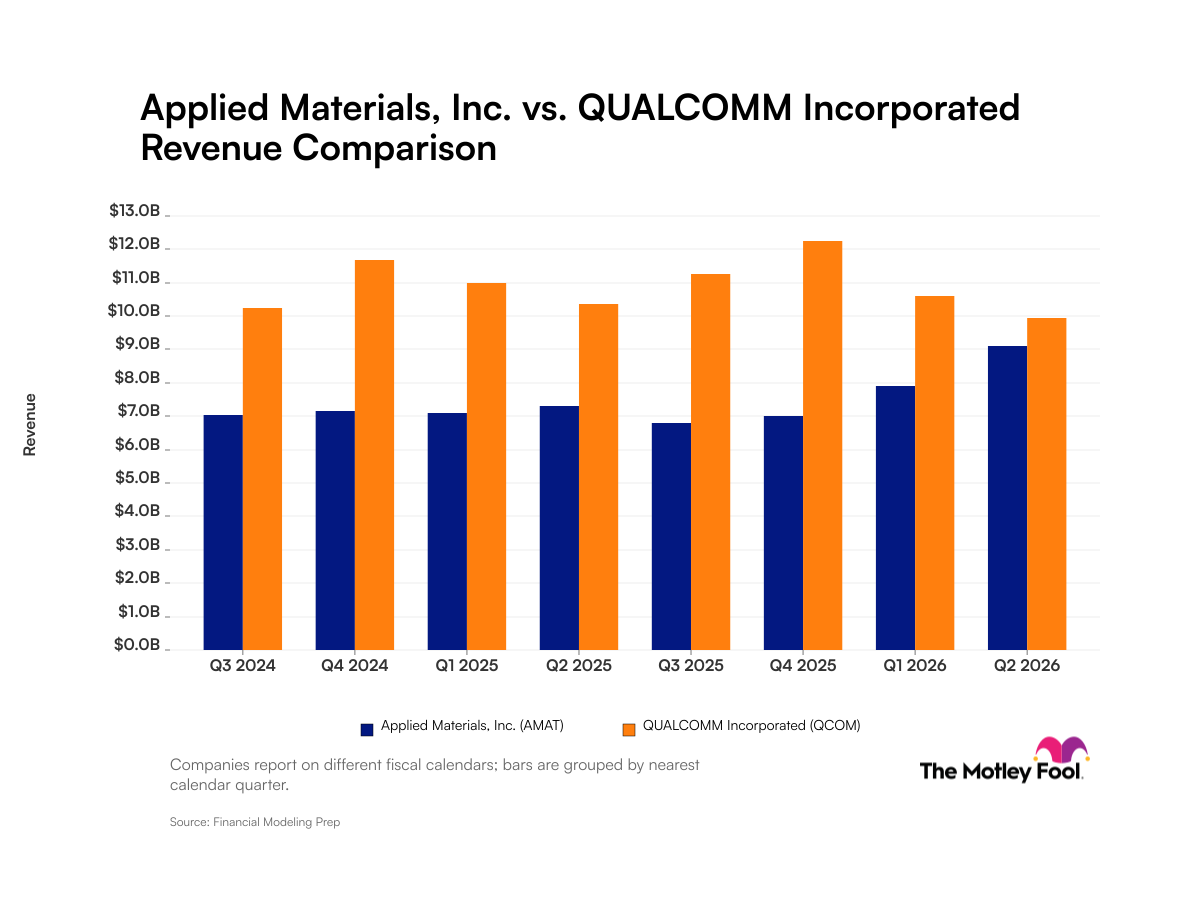
Applied Materials has nearly closed a significant revenue gap with Qualcomm, posting consecutive quarterly gains driven by AI infrastructure demand for semiconductor manufacturing equipment. Meanwhile, Qualcomm faces sequential revenue declines as the mobile handset market matures, though the company is attempting to pivot toward AI data center opportunities.
Our take is based on reporting first published by The Motley Fool.